If you’ve ever felt frustrated looking at your credit,
Dated: April 28 2026
Views: 21
If you’ve ever felt frustrated looking at your credit score, you’re not alone. The good news is that improving your credit score isn’t as complicated as it seems—and with the right strategy, you can start seeing results faster than you think.
Your credit score plays a huge role in your financial life. It affects your ability to buy a home, get approved for a loan, and even secure better interest rates. Whether you’re trying to qualify for a mortgage or just want more financial freedom, here’s a practical, real-world guide to help you boost your numbers.
This is the single most important factor in your credit score improvement journey.
Late payments can stay on your credit report for years. Setting up autopay or reminders can make a huge difference. Even one missed payment can drop your score significantly, so consistency is key.
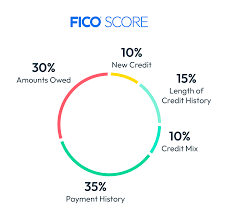
SEO tip: Payment history makes up about 35% of your FICO score.
Your credit utilization ratio is how much credit you’re using compared to your limits.
For example, if you have a $10,000 limit and you’re using $5,000, that’s 50% utilization—which is too high.
👉 Aim to keep it under 30% (ideally under 10% for the best results).
Paying down balances—even partially—can quickly boost your score.
It might seem smart to close unused credit cards, but this can actually hurt your score.
Why? Because the length of your credit history matters. The longer your accounts have been open, the better it looks to lenders.
Instead of closing accounts, keep them open and use them occasionally.
Every time you apply for a loan or credit card, a hard inquiry is added to your report.
Too many inquiries in a short time can lower your score and signal risk to lenders.
If you’re planning a big purchase—like buying a home—try to avoid applying for new credit beforehand.
You’d be surprised how often mistakes show up on credit reports.
Look for:
Incorrect balances
Accounts that aren’t yours
Payments marked late that were actually on time
Disputing errors can lead to a quick credit score boost.
Having a mix of credit—like credit cards, auto loans, and personal loans—can help your score.
But don’t open new accounts just for the sake of it. Only take on credit you actually need.
Improving your credit score fast is possible, but it still takes some time and discipline.
Small habits—like paying on time and keeping balances low—add up over time.
Improving your credit score isn’t about being perfect—it’s about being consistent. Focus on the basics, avoid common mistakes, and stay patient.
If you’re planning to buy a home or invest in real estate, having a strong credit score can save you thousands in interest and open more opportunities.
If you want help understanding where you stand or how to position yourself to buy, feel free to reach out. I’m always happy to point you in the right direction.
[Your Full Name]
[Your Address]
[City, State ZIP]
[Phone Number]
[Email Address]
[Last 4 Digits of SSN]
[Date]
Sent via Certified Mail
To:
Experian / Equifax / TransUnion
[Credit Bureau Address]
To Whom It May Concern:
I am writing to formally dispute inaccurate and/or unverifiable information currently being reported on my consumer credit report. Pursuant to my rights under the Fair Credit Reporting Act, specifically Sections 611 and 623, I am requesting a reasonable investigation into the accuracy and completeness of the items listed below.
The following account information appears to be inaccurate, incomplete, misleading, or unverifiable:
Creditor Name: [Creditor Name]
Account Number: [Last 4 digits only]
[Choose and customize]
This account does not belong to me.
The payment history is inaccurate.
The balance being reported is incorrect.
This account has been duplicated.
This account was previously paid/settled.
The dates reported are inaccurate.
The account status is incorrect.
The information cannot be properly verified.
Because this information is inaccurate or unverifiable, I request that the account be corrected or deleted from my credit file immediately pursuant to the FCRA.
Additionally, under Section 611(a)(6) of the FCRA, I request that you provide:
A description of the procedures used in your investigation
The name, address, and telephone number of any furnisher contacted
Copies of any documentation relied upon during the investigation
If you are unable to verify this information through a reasonable investigation, the disputed information must be deleted from my consumer report.
I have enclosed copies of supporting documentation, including:
Copy of identification
Proof of address
Relevant account statements
Supporting payment records/correspondence
Please complete your investigation within the time period required by federal law and send me an updated copy of my credit report reflecting any corrections or deletions made.
Thank you for your prompt attention to this matter.
Sincerely,
[Your Signature]
[Your Printed Name]
Send by certified mail with return receipt
Include only copies of documents
Never send originals
Keep a copy of everything
Dispute 1–5 accounts at a time for better clarity
Experian
P.O. Box 4500
Allen, TX 75013
Equifax Information Services LLC
P.O. Box 740256
Atlanta, GA 30374
TransUnion Consumer Solutions
P.O. Box 2000
Chester, PA 19016
You can also file complaints with:
Consumer Financial Protection Bureau
Or the:
Federal Trade Commission
Fernando Jimenez brings more than 30 years of real estate and city experience to our clients. Before becoming a Realtor, he spent decades with the City of San Antonio and worked as a licensed Home Ins....
 Information provided courtesy of LERA MLS. IDX information is provided exclusively for consumers' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information is believed to be accurate but not guaranteed. Provided courtesy of LERA MLS. Copyright 2026 LERA MLS, All Rights Reserved. Data last updated September 21, 2026 5:31 PM UTC
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than United Realty Group may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 21, 2026 2:54 PM UTC
Show More...
